Why Is My Bank Asking For A Collateral Assignment of Life Insurance And What Does It Mean?
Everything is done for you to buy that practice, you have been approved by the bank, the lease has been signed, and the bank is ready to disburse the loan so you can be a practice owner! There is just one issue, they need you to collaterally assign them a life insurance policy. Now usually no one ever explains what this actually means and what you should do.
Contact Us Today
Should you assign your personal policy to them? Do you need to get a new one?
There are many different options and while no one will stop you from doing either of them, there are different considerations to be made when making that decision.
What is a Collateral Assignment?
When getting a loan for a dental practice, the bank will almost always require the borrower to assign to them a life insurance policy that will cover the amount of the loan for the term of the loan. It basically means that if the borrower were to pass away during the loan term, the bank still gets the money they were owed, and the loan is paid off by that life insurance. If that is a requirement from your bank, then there is no getting around having to assign the policy to them with the help of your agent.
Should I Assign My Current Policy or Get Another One?
The first point we always help our clients to make is that personal life insurance is just that, personal! It is almost always in someone’s best interests to separate church and state in a sense when thinking about their own finance’s vs the finances of their business. If you already have a personal life insurance policy, that’s great! That policy is meant for your family and next of kin if you pass away.
However, while the prospect of having to get life insurance again may not be what you were hoping for, the flip side is that if you were to assign that policy to the bank and then pass away, your family will most likely not get the payout they were planning to live on. Reason is, because the bank will need to satisfy their loan, and that is exactly what is avoided with the concept of separating business vs personal finances and getting a second policy!
What Does Getting a Second Policy Entail?
It’s fairly simple since it is the exact same process as the first! Starting with figuring out the term and amount of the loan, getting a quote, filling out the application and then getting the policy! Term life insurance tends to be very cost effective for most people when it comes to the amount and terms one needs for the collateral assignment. So, it is almost never an issue with budgeting or cost as well!
There is also the added benefit, because it is exclusively tied to the loan, if you pay it off early you can always cancel the policy since it wouldn’t be needed anymore. Along with that, since the bank is not the beneficiary of the policy, but the assignee is, there is still a beneficiary as well (still usually your family or next of kin). So, if the worst still does come to pass and the practice is paid 50% off, then the bank still gets what is owed to them. But then the beneficiary may get something that they weren’t expecting during a hard time too.
I hope that helps all the new practice owners out there! We at CFS Dental Division are always here to help and work in your best interest to figure out what is going to not just be best for you now, but in the future as well!
Written by: TJ Stanton
Wondering if your dental malpractice premium still makes sense? See how our annual review and remarketing process works, and when to shop the market.
Dental Malpractice Insurance in New York: What Every Dentist Should Know
A plain English look at how dental malpractice insurance works in California, plus the questions our team walks through with practice owners. Let's talk.
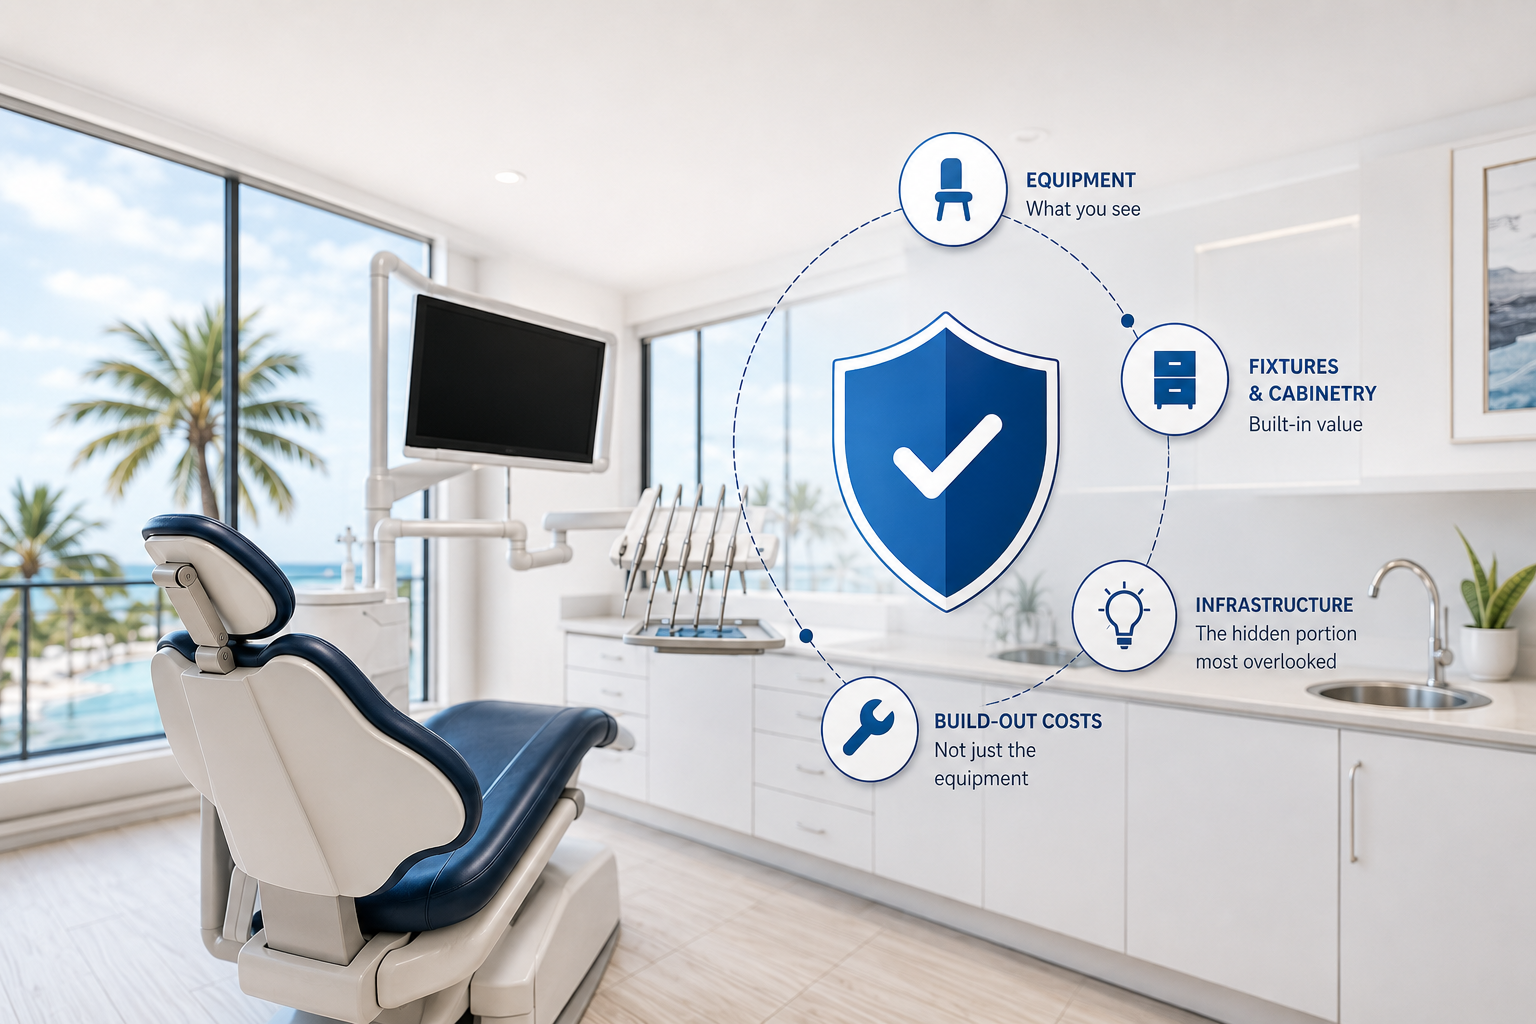
How much is enough? Defining business personal property and uncovering the “hidden” portion many practice owners miss
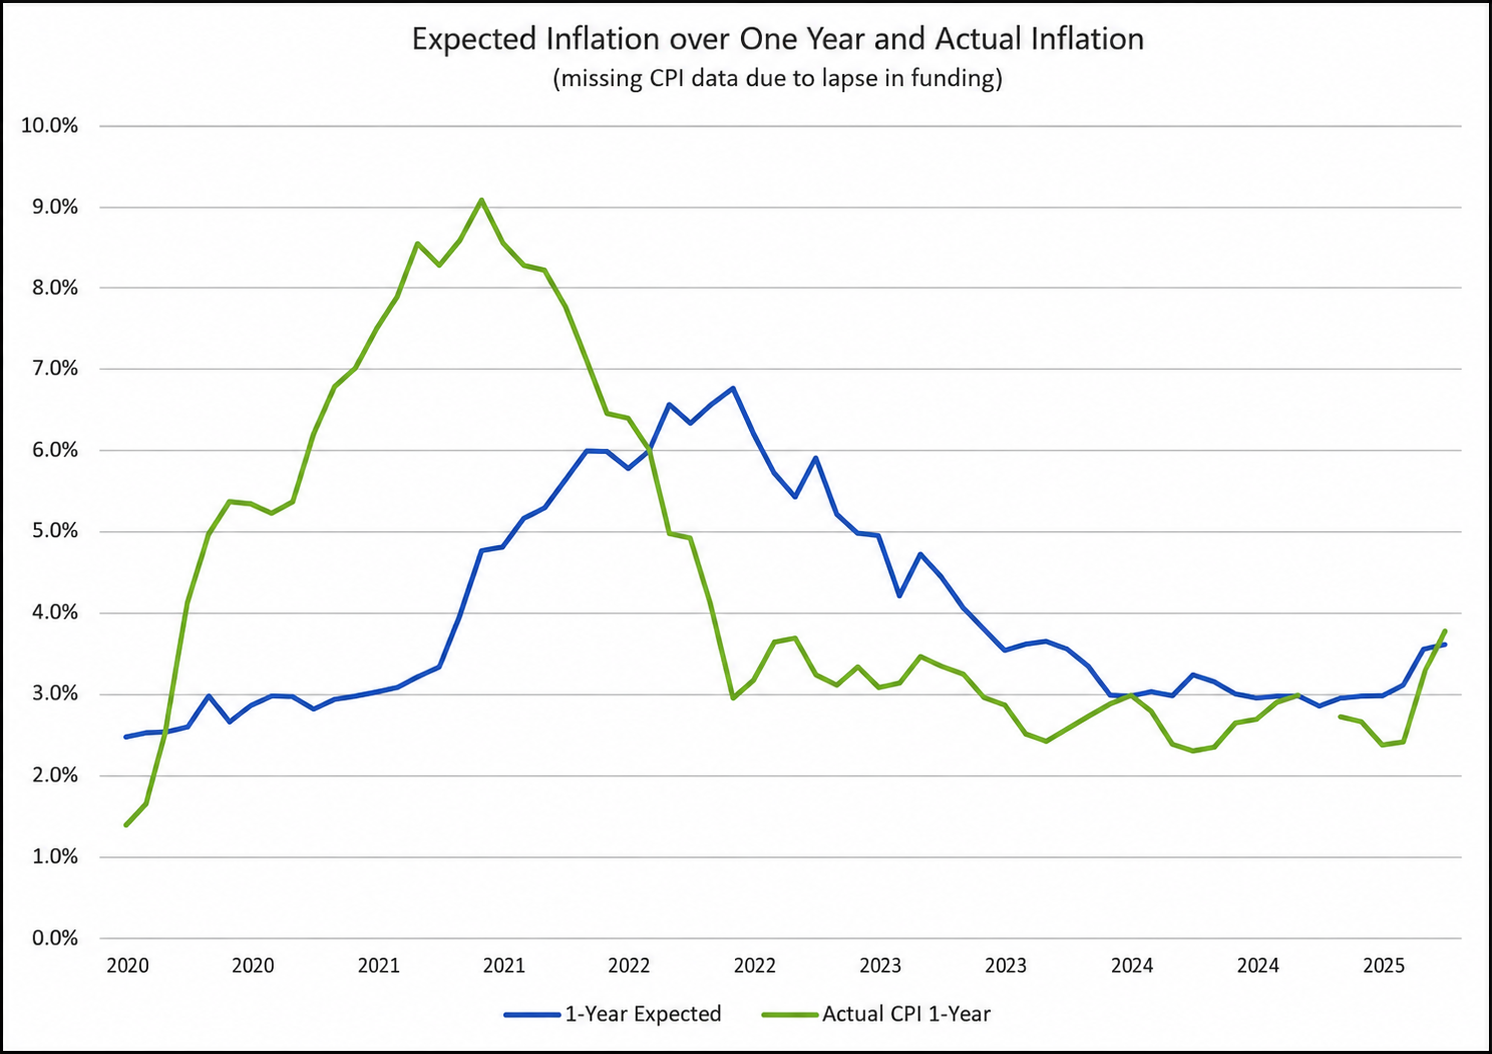
The Benefits of COLA
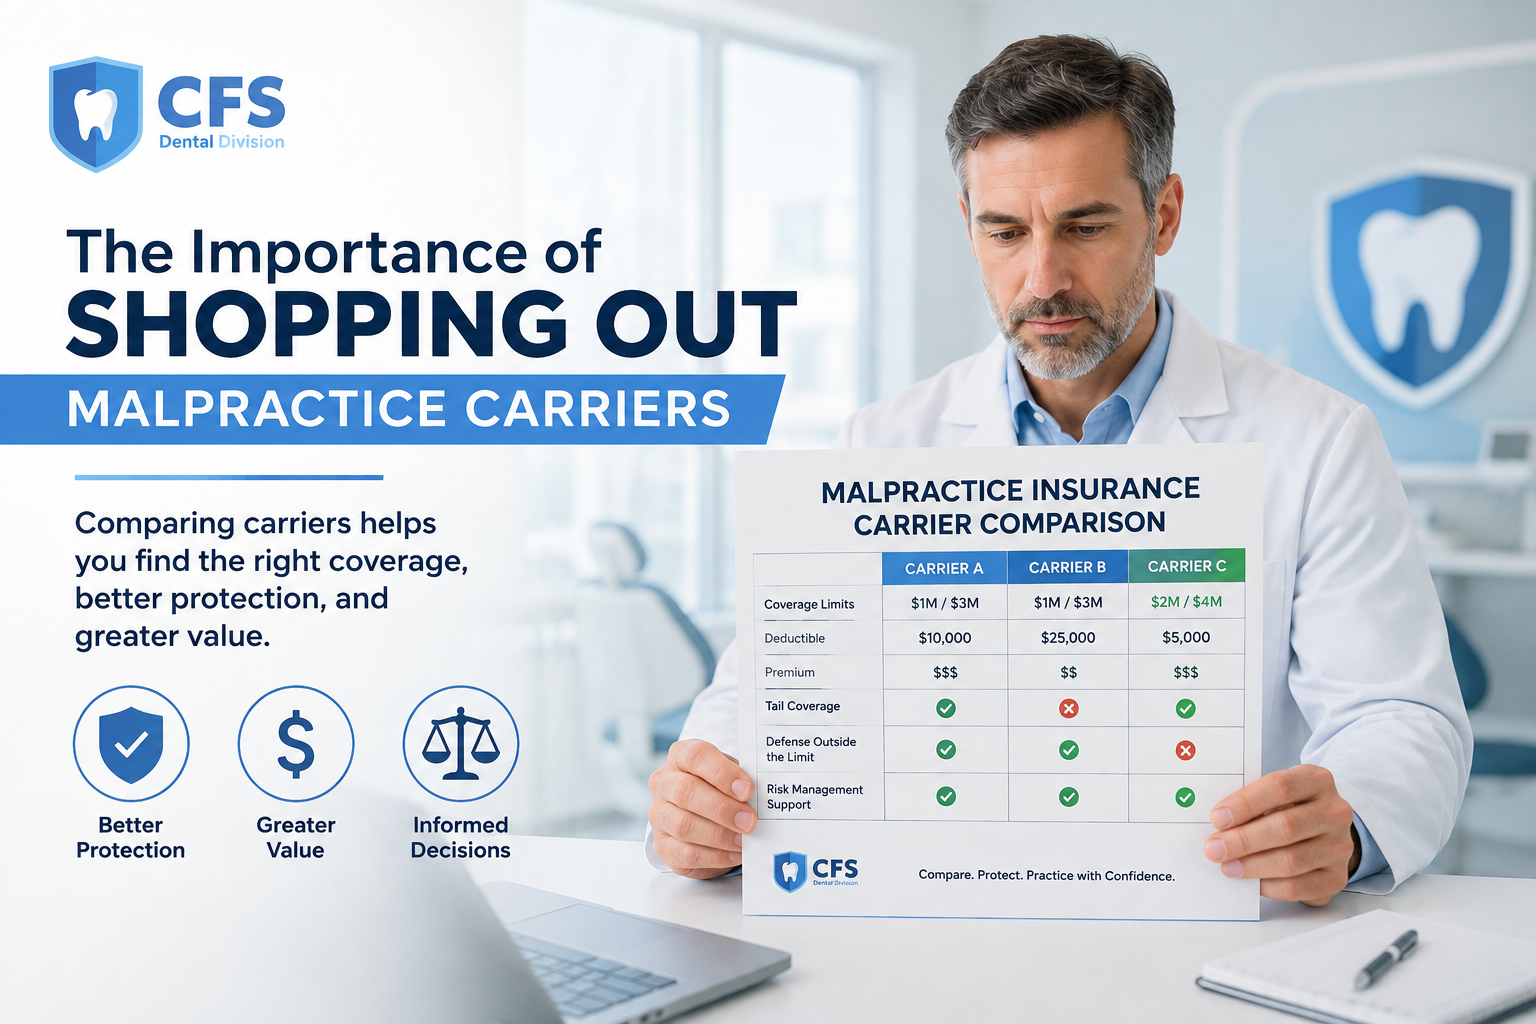
The Importance of Shopping Out Malpractice Carriers
Surplus Lines Insurance: What It Is, Why It Exists, and When You Might Need It
Why Focusing on Protection - Not Just Price - Is Most Important When Buying Business Insurance For Your Dental Practice.
Buying Your First Dental Practice: An Insurance Checklist for New Owners
Claims Made vs. Occurrence Malpractice Policies: Exploring Your Options Without Fear