Business Overhead Expense vs. Personal Disability Insurance: Why Practice Owners Usually Need Both
If you own a dental practice, do you need business overhead expense insurance on top of your personal disability policy?
Here is a conversation we have at CFS Dental Division more often than you might think. A practice owner tells us they are "fully covered" for disability. We ask to see the policy. It turns out to be a solid personal disability policy, exactly the kind we would recommend. And then we ask the follow up question: if you could not practice for six months, who pays the rent, the staff, and the equipment loan?
Usually there is a pause.
Personal disability insurance and business overhead expense insurance (most people just call it BOE) sound like they do the same thing. They do not. One protects you and your household. The other protects the practice you built. If you own a practice, or are about to, it helps to understand exactly where one stops and the other starts.
What Personal Disability Insurance Is For
A personal disability policy is designed to replace a portion of your income if an illness or injury keeps you from working. The benefit is paid to you, and you decide how to use it: the mortgage, groceries, tuition, retirement contributions, your student loan payment. It is about keeping your household running.
For dentists, the definition of disability inside that policy matters enormously, which is why we spent our entire September post on true own-occupation coverage. The short version: a hand, back, or vision issue that would barely slow down most professionals can end a clinical career, so the way a policy defines your occupation deserves a careful read. You can learn more on our disability insurance page.
What a personal policy generally is not designed to do is keep your practice open. A typical benefit is sized to your personal income, not to the cost of running an office with a team, a lease, and financed equipment.
What Business Overhead Expense Insurance Is For
Business overhead expense insurance is designed to reimburse eligible business expenses while you are disabled, so the practice can keep operating while you recover. Every policy has its own list, but the expenses commonly considered eligible include:
- Rent or mortgage payments on the office
- Staff salaries and benefits (generally excluding your own pay)
- Utilities, phone, and software subscriptions
- Equipment leases and, in many cases, loan payments on the practice
- Professional liability and other business insurance premiums
Some policies also allow the cost of a replacement dentist to count as a covered expense, though how that works varies quite a bit from carrier to carrier and is worth confirming in writing.
BOE is usually built as a shorter term product. Benefit periods are commonly in the range of one to two years, because the goal is to bridge a recovery or give you time to make a decision about the practice, not to replace income for decades. Policies typically have an elimination period (the waiting period before benefits begin), and shorter waiting periods generally cost more.
Do You Know What Your Practice Costs to Keep the Lights On?
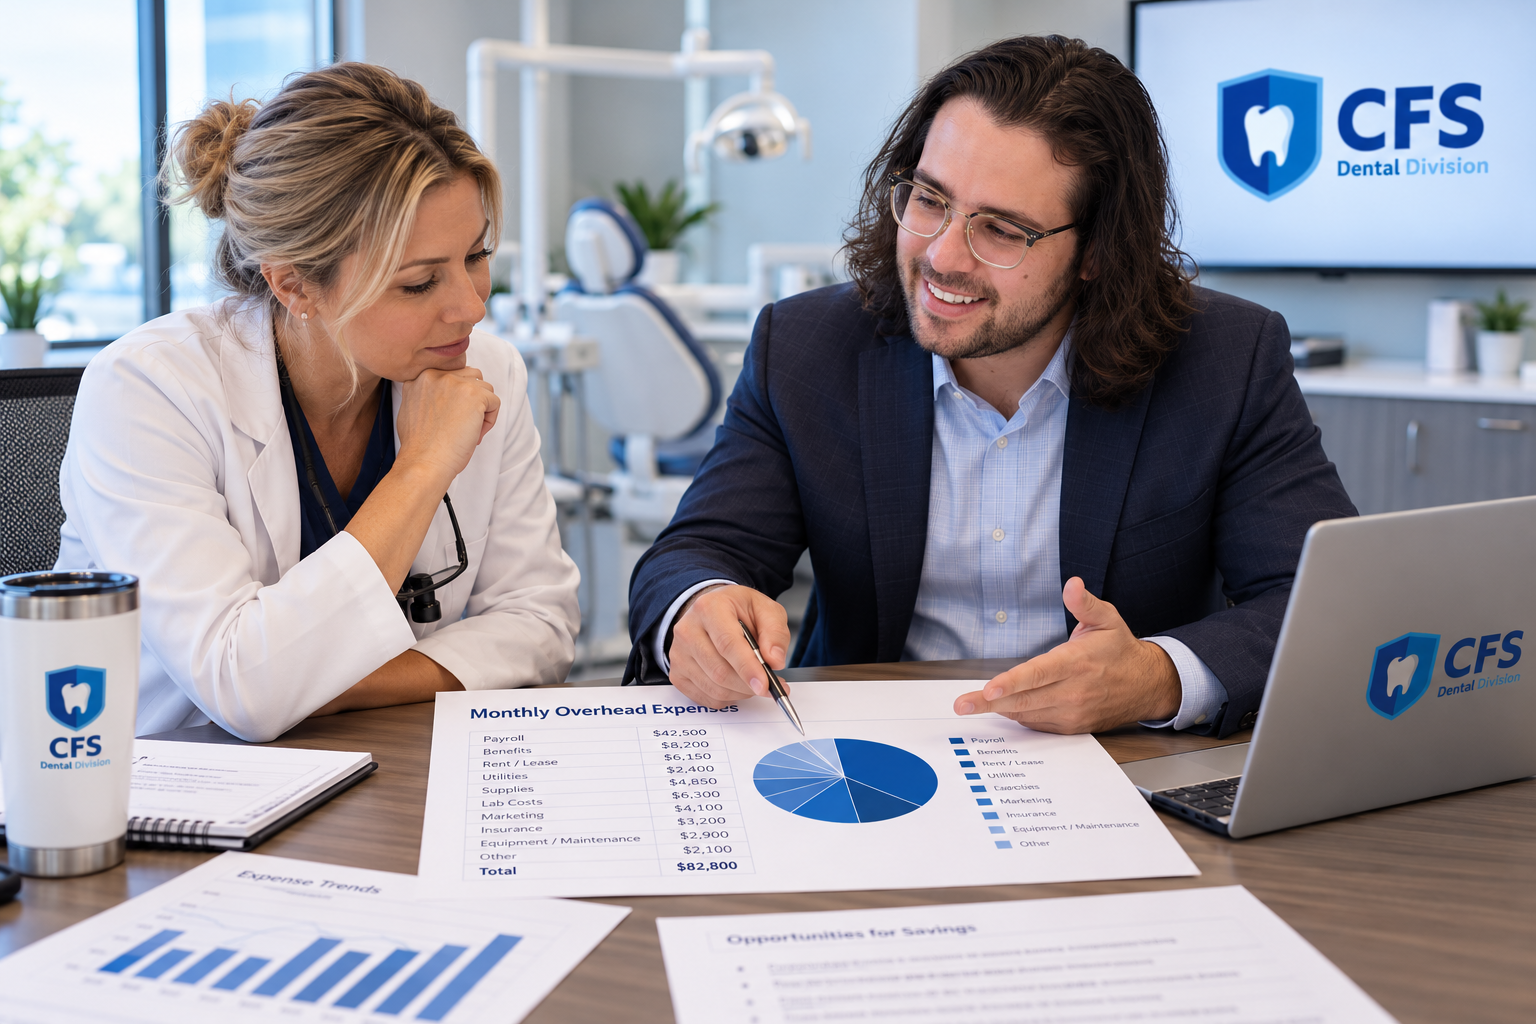
Most owners know their production number to the dollar and their overhead number only roughly. Send us a recent profit and loss statement and we will help you translate it into a realistic monthly overhead figure, then compare it to any coverage you already have. Reach out through our contact page to get started. No cost, no obligation.
A Side by Side Look
- Who receives the benefit. Personal disability pays you. BOE reimburses the practice for qualifying expenses.
- What it is sized to. Personal disability is sized to your income. BOE is sized to your monthly overhead.
- How long it typically pays. Personal disability can run for years, sometimes to a stated age. BOE is commonly limited to a shorter benefit period.
- How taxes usually work. This is general information, so please confirm with your CPA. Personal disability premiums are commonly paid with after tax dollars, which is often why the benefits can be received tax free. BOE premiums are commonly treated as a deductible business expense, and the benefits are then generally treated as taxable income to the business, offset by the deductible expenses they reimburse. How a policy is owned and paid for affects the outcome, so this is one to set up deliberately rather than by default.
Why "I'll Just Use My Personal Policy" Usually Falls Short
Let's run a simple example with round numbers. Say your personal disability benefit is designed to replace a meaningful share of your take home pay, and your practice overhead runs well into five figures a month. If you are out of the operatory and only your personal policy pays, that benefit now has two jobs: your household and your practice. It almost never covers both.
What tends to happen next is not pretty. Owners drain savings to make payroll, staff leave because they sense uncertainty, patients drift to other offices, and the practice is worth noticeably less by the time the owner is ready to return or sell. BOE exists precisely to prevent that slide.
It buys time, and time is what protects the value of the practice.
Who Should Be Thinking About BOE
- New practice owners and startups. Overhead is high, reserves are thin, and loan payments do not pause.
- Dentists buying an existing practice. Acquisition lenders often care a great deal about disability protection, and some require it.
- Solo owners. When you are the primary producer, your absence affects every line of revenue.
- Partners and group owners. BOE protects your share of the overhead, but partnerships should also look at how a buy-sell agreement handles a long term disability. That is a contract question as much as an insurance question, and it is one we often review alongside our legal and contract review partners.
Associates who do not own a practice generally do not need BOE. Their focus should be a strong personal disability policy, and ideally one purchased early, while they are healthy and before premiums climb with age.
Sizing It Without Overbuying
A few habits help keep BOE right sized:
- Base the benefit on actual monthly overhead from your financials, not a guess.
- Leave your own salary and personal draw out of the calculation. That is what your personal policy is for.
- Revisit it when the practice changes: a new hire, a new lease, a second location, a big equipment purchase.
- Line up the elimination periods on your BOE and personal policies so you understand what you will be covering out of pocket in the first weeks.
- Check carrier financial strength. We look at ratings from groups such as AM Best and Moody's, because a policy is only as good as the company standing behind it.
Quick checklist
Personal disability insurance
- Protects your household income
- Pays you directly, often for years
- Read the own-occupation definition closely
Business overhead expense insurance
- Reimburses eligible overhead like rent, payroll, utilities, and loan payments
- Usually pays for a shorter benefit period
- Set ownership and payment up deliberately with your CPA
The Bottom Line
Relying on a personal policy alone forces one benefit to cover two very different sets of bills. At CFS Dental Division, we work exclusively with dental professionals, and we do not believe in one size fits all advising. A startup owner with a new build out and a 20 year veteran with a paid off office need very different answers. Our job is to make sure your personal coverage protects your family and your overhead coverage protects your practice, without gaps and without paying for the same thing twice. You can also reach us directly at info@cfsdentaldivision.com.
Disclaimer: This article is provided for general informational and educational purposes only. It is not legal, tax, or insurance advice, and it does not describe or guarantee the terms of any specific policy. Eligible expenses, benefit periods, elimination periods, tax treatment, and policy definitions vary by carrier, by state, and by individual circumstance. Coverage is subject to the terms, conditions, exclusions, and limits of the policy actually issued. Please consult a licensed insurance professional, a qualified tax advisor, and, where appropriate, legal counsel before making decisions about your coverage.
President, CFS Dental Division
Own a practice or about to buy one? Let's review your coverage.