Life Insurance: Term Life V.S. Whole Life
There will come a time in your life where you will be introduced to life insurance. It may be from a salesman, a letter in the mail, or your workplace may offer it to you. You might ask, what is the point of life insurance and why do I need it?
Contact Us Today
Life insurance is a financial safety net for your loved ones in the tragic event of your passing. Likewise, a loan may require life insurance as well. There are two main life insurance policies, term life insurance and whole life insurance. They both serve the same core purpose; however, they differ in structure, cost, and benefits.
Term Life Insurance
Term life insurance provides you with coverage for a set amount of time. Most term life insurance policies are set between 10-to-30-year terms. This means that you are covered by life insurance during that timeframe. For example, a 30-year-old obtaining a 20-year term life insurance policy is covered until they reach age 50. Once they reach age 50, the policy no longer covers them and their family unless renewed or converted.
The main highlight of term life insurance is the affordability. Term life insurance uses a fixed payment throughout the duration of the term length. The younger a person is when purchasing a policy, the more cost effective the rate will be. When purchasing life insurance, be sure that your policy has the word ‘renewable’ or ‘convertible’ included. Those types of term life insurance policies guarantee that you will be able to continue your life insurance coverage either as another term policy, or as a whole life policy. Renewable or convertible policies also do not usually require a new medical exam as well.
The downsides of a term policy are fairly straight forward. Term policies only offer death benefits and nothing further. This can dissuade some as they may see term policies as paying the premium just in case something bad happens. Also, once a term policy matures, your premiums will adjust. This means that after a term ends, it may become more expensive than before to renew your term. There will be a reason to purchase term insurance, and that reason should outweigh the limiting factors of a term life insurance policy.
Whole Life Insurance
The other aforementioned life insurance is a whole life insurance policy. Whole life insurance offers coverage for the entirety of a person's life or once a person reaches 100 years old. The main feature of whole life insurance, outside of the death benefit, is the cash value that the policy can hold which grows tax deferred.
As stated, whole life policies have a cash value element to them that a term policy does not. On top of the death benefits, whole life policies have a minimum interest rate that grows the cash value along with your premium payments. On top of this, you do not pay taxes on the cash value growth while the policy remains in place. A whole life policy can be seen as an investment vehicle for those that have maxed all their retirement options and wish to have another way to invest their money. Whole life insurance policies offer everything a term policy does, but with a cash value and lifelong protection.
While whole life insurance policies offer a lot, they may not be great for everyone. Whole life policies are more expensive than term policies since you are paying extra because of the cash value. A person that is more attracted to a lower price tag could opt for a term policy instead.
Whole life policies can also be hard to understand. The complexity of the cash value growth and when taxes finally come into effect make it harder to judge how much of that cash value is actually liquid. If you have a lower income, or your retirement options are not maxed out, then a whole life may not be the best choice for you.
Which Type Is Right For You
By this point, you may be favoring one type over the other but pause and think of your current situation. Do you have a family? Do you make enough to cover a premium for multiple years? Are my retirement accounts at capacity?
Buying life insurance is not a rash decision as it is a policy you hold for at least a decade. If you are young, budget-conscious, or are concerned with protecting your family, then term life insurance is better for you. It offers a lower premium given your current age and gives coverage for the set amount of time that you specify. If you are nearing retirement but are still working and you are looking for another way to invest, then whole life insurance can be the better choice.
Insurance as a whole depends on your current situation in order to meet you where you are. It is best to make an educated decision, rather than pay for an expensive one for years to come.
Written by: Nate Young
Wondering if your dental malpractice premium still makes sense? See how our annual review and remarketing process works, and when to shop the market.
Dental Malpractice Insurance in New York: What Every Dentist Should Know
A plain English look at how dental malpractice insurance works in California, plus the questions our team walks through with practice owners. Let's talk.
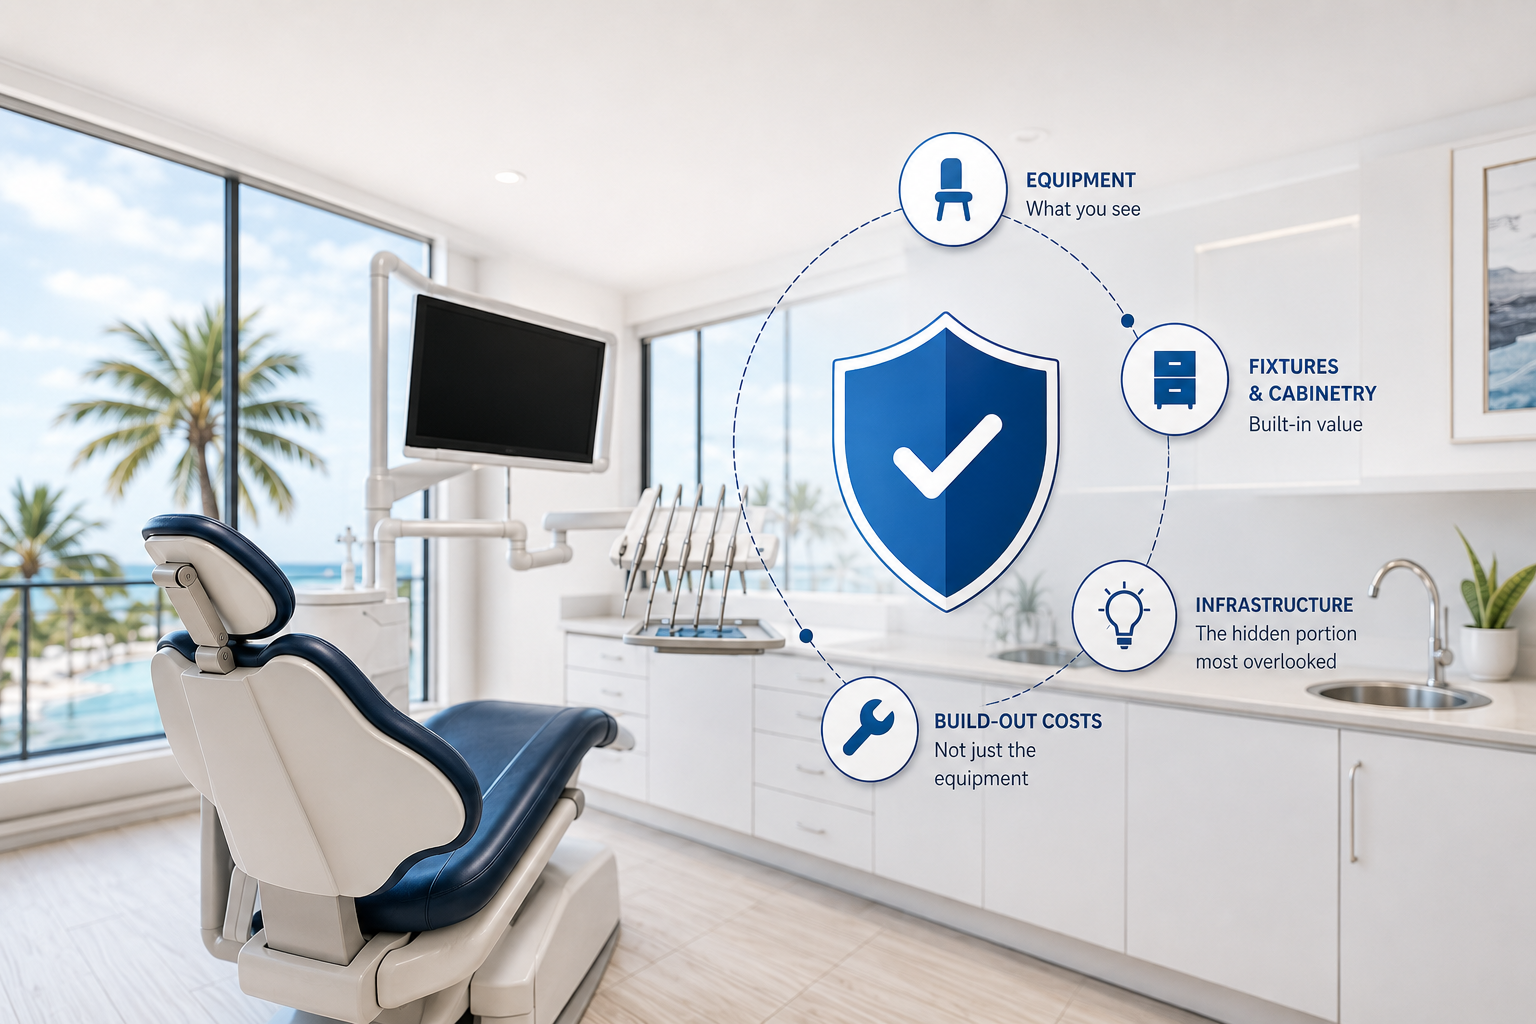
How much is enough? Defining business personal property and uncovering the “hidden” portion many practice owners miss
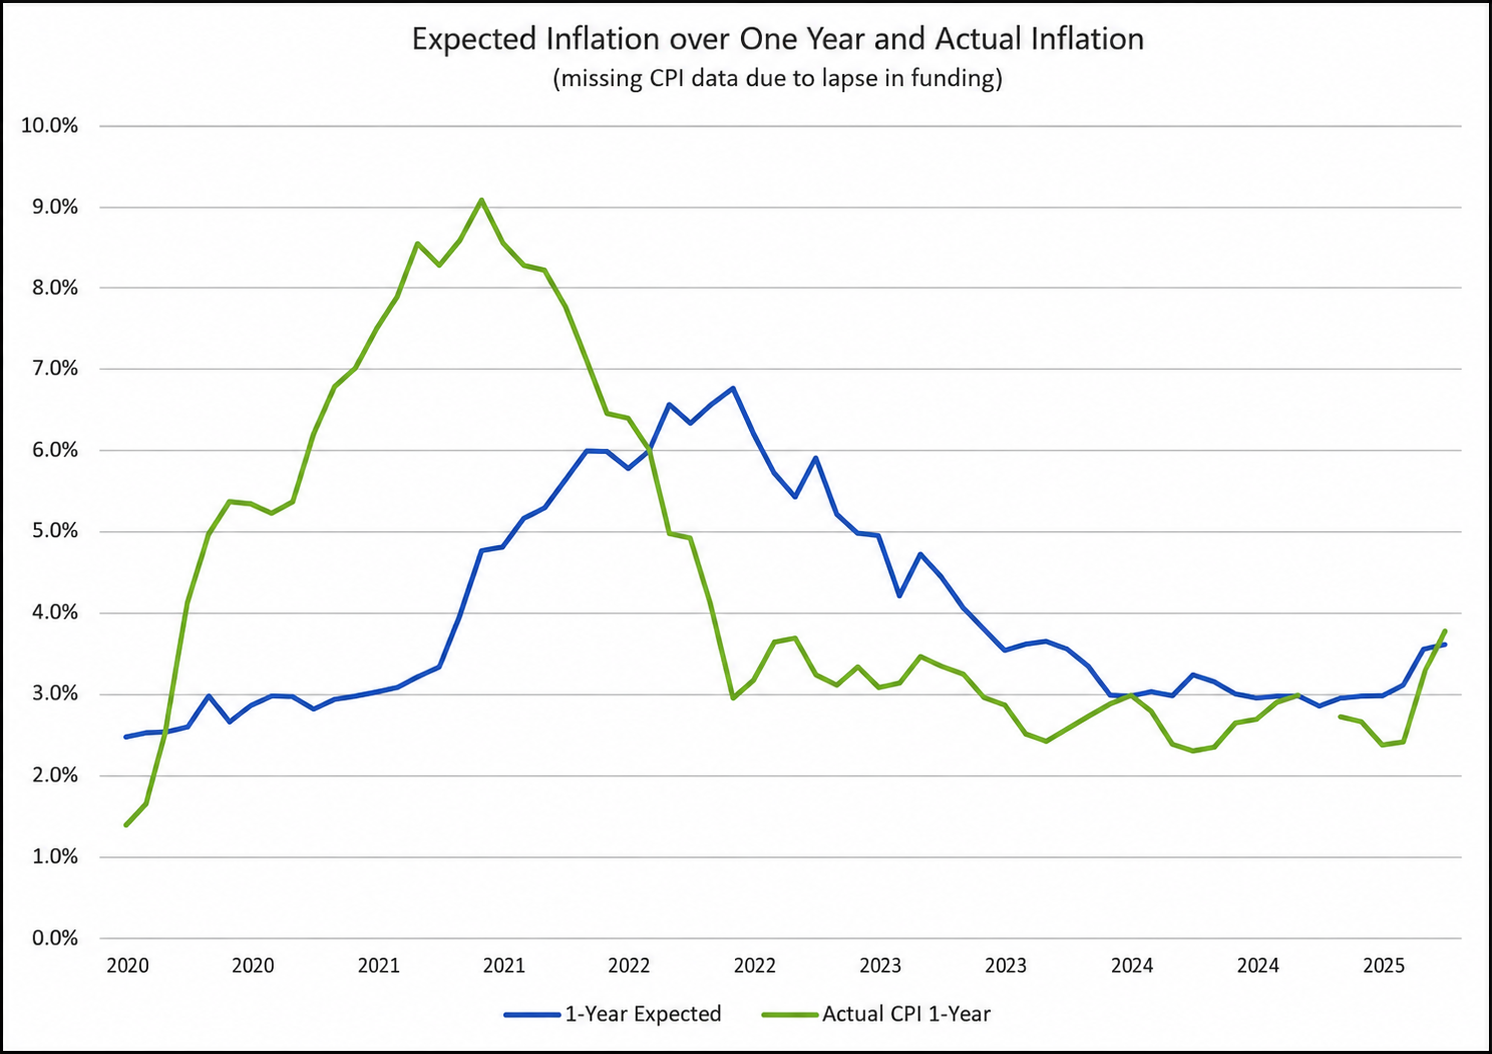
The Benefits of COLA
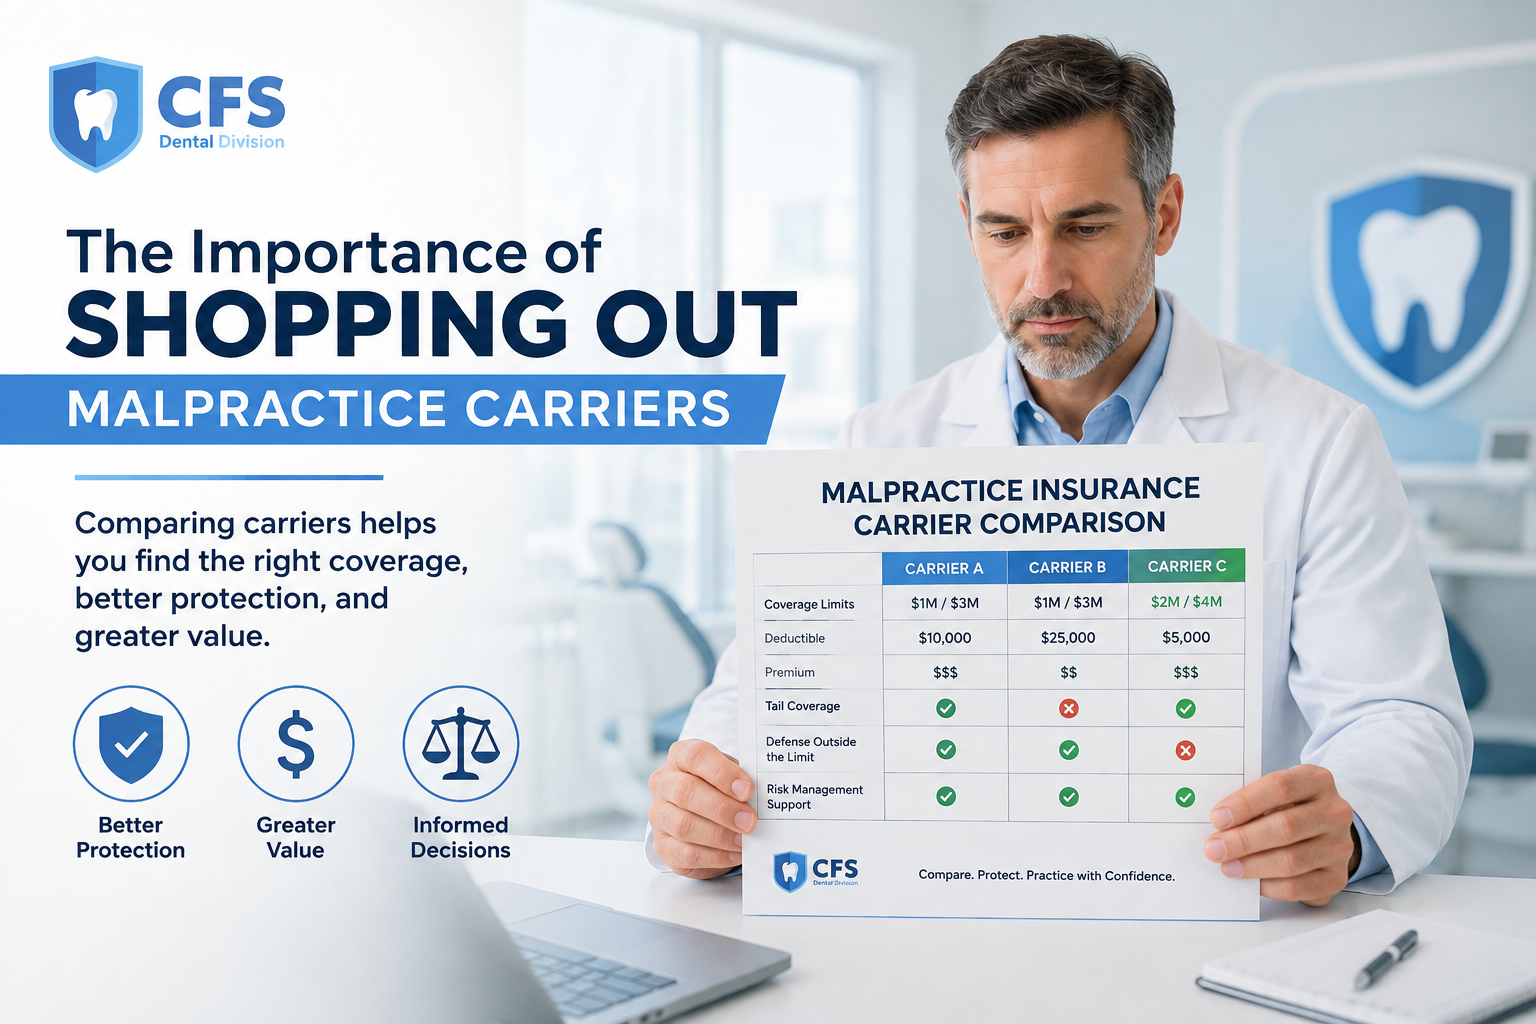
The Importance of Shopping Out Malpractice Carriers
Surplus Lines Insurance: What It Is, Why It Exists, and When You Might Need It
Why Focusing on Protection - Not Just Price - Is Most Important When Buying Business Insurance For Your Dental Practice.
Buying Your First Dental Practice: An Insurance Checklist for New Owners
Claims Made vs. Occurrence Malpractice Policies: Exploring Your Options Without Fear