What Happens to Your Dental Practice Insurance When You Buy or Sell a Practice?
When buying or selling a dental practice, what happens to your dental practice insurance?
When buying or selling a dental practice, there are several things to coordinate: financing, contracts, employees, equipment, leases, and closing dates. Insurance is one of the most important pieces, and the time to address it is early rather than later. When ownership changes, the insurance needs of the practice may change considerably.
Buying a Dental Practice
When buying a practice, don’t assume that you can simply take over the seller’s policies. Your coverage should be reviewed and coordinated with the date you officially take ownership. This may include your:
- Business interruption insurance
- Workers’ compensation
- Dental malpractice insurance
- Cyber insurance
- Property and liability coverage
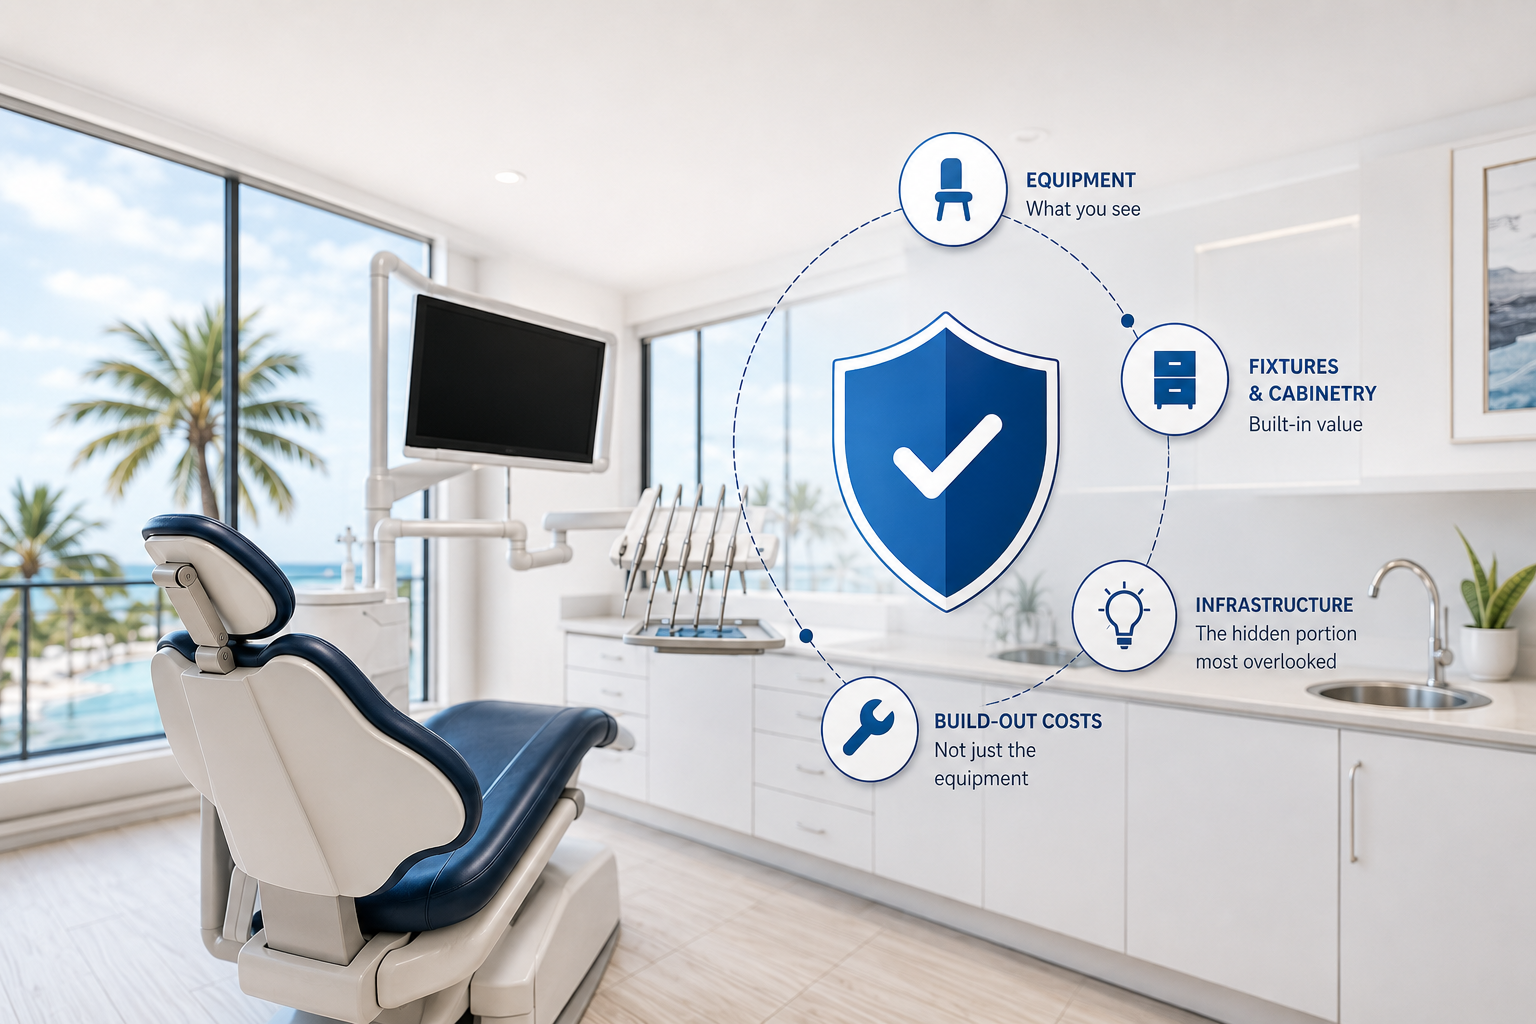
It’s also a good idea to make sure the coverage is correct for the practice you’re buying. Has the practice purchased additional equipment? Increased revenue? Added employees? These changes may affect the amount and types of coverage you need.
Selling a Dental Practice
Insurance is an important consideration when selling a dental practice, and one of the most significant policies to check is your dental malpractice insurance. You may need to arrange coverage for claims made after the sale for treatment you provided before it. This can involve purchasing options such as tail coverage.
It’s also smart to review your other coverages, such as property, liability, workers’ compensation, and cyber, to decide when each one should end. Planning this before the closing date helps you avoid an unnecessary gap in coverage, or paying for coverage you no longer need.
Don’t Ignore Business Interruption
A property policy covers your business property after a loss. But what if a fire, a water loss, or another covered event forces you to close temporarily?
Business interruption coverage can help replace lost income when you can’t operate and see patients in the chair because of a covered loss. This is a key consideration for any practice owner.
It’s not only about safeguarding your equipment. You’re safeguarding the income that sustains your practice and your livelihood.
Don’t Forget the Lease
Depending on the landlord, your lease may have unique insurance requirements, such as specific limits of liability, additional insured status, or other terms you might not be familiar with.
When ownership changes, make sure those requirements are noted and that the new policy meets them, so you’re meeting your obligations under the lease agreement.
Start Before Closing
Start planning your insurance early. It’s much easier to handle when you have time and don’t need to rush. Whether you’re buying or selling a dental practice, it’s always best to get your insurance advisor’s input at the beginning of the transaction. That gives you time to see what’s covered and what might be missing, so you aren’t scrambling at the last minute and can feel confident in your protection at closing.
Quick checklist
If you’re buying
- Start new policies on your ownership date
- Update coverage for equipment, revenue, and staff changes
- Meet the lease’s insurance requirements
If you’re selling
- Ask about malpractice tail coverage
- Set end dates for property, liability, workers’ comp, and cyber
- Avoid gaps and overlapping coverage at closing
The Bottom Line
Whether you’re purchasing your first practice, acquiring another one, or planning for retirement, insurance should always be part of the conversation. CFS Dental Division helps dentists handle these transitions smoothly by reviewing and coordinating all of their insurance needs.
Buying or selling a practice? Let’s review your coverage.
Talk to an advisor