The Benefits of COLA 


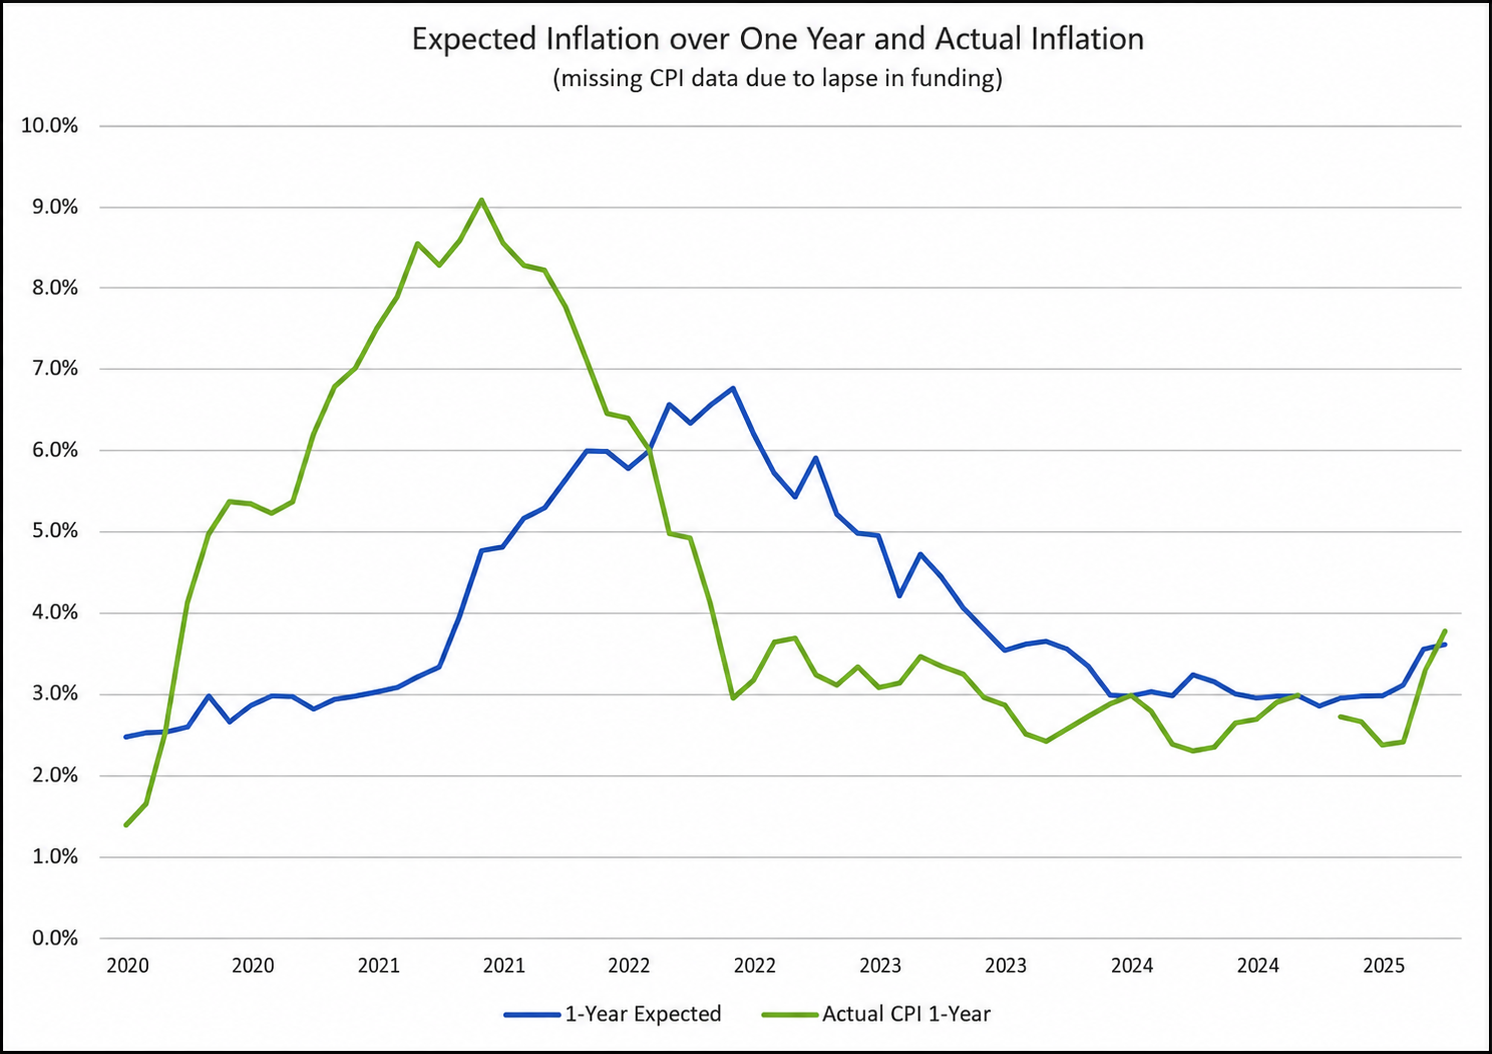
Inflation has been a major topic surrounding the economy over the past few years. A 2 -3% rate of inflation is normal and expected, but recently the year-over-year rate has been above that. Inflation leads to your purchasing power going down and the cost of everything goes up to account for the reduced value of the dollar. It mainly affects those on a fixed income but can also play a role in a person’s financial planning. If your investments or your wages don’t appreciate past the rate of inflation, then you fall behind and the money you do have has less value. Per the chart below, we’ve experienced high inflation over the past few years and are finally getting back to a more regular rate. 


How does this affect insurance?

Well, if you have a disability insurance policy, you may notice a rider on the policy that can counteract inflation. It is called the Cost-of-Living Adjustment (COLA), and its main purpose is to increase the monthly disability claim benefit on your policy by a few percentage points, so your buying power doesn’t decrease.


To understand the financial impact of a 3% compounded COLA rider on a $10,000 monthly benefit, review this 15-year claim timeline:

  • [Year 1] $10,000 / month (Base Benefit)
  • [Year 5] $11,255 / month (+12.5% increase)
  • [Year 10] $13,048 / month (+30.5% increase) │
  • [Year 15] $15,126 / month (+51.2% increase)


Historically, US inflation goes up by 35-55% every 15 years. Adding this feature to your disability may cost more in the short-term to add to the policy but it will add a significant benefit if you ever do go on claim. It’s important to have a long-term plan of the purpose of the insurance and how it can best benefit you when you go to use it. 


Written by: Jeremy Alfano, Chief Operating Officer  - CFS Dental Division


Bright dental clinic with a white patient chair, cabinets, and large window overlooking city buildings
October 7, 2026
When buying or selling a dental practice, there are several things to coordinate: financing, contracts, employees, equipment, leases, and closing dates. Insurance is one of the most important pieces, and the time to address it is early rather than later.
Desk by ocean with “Is It Time to Revisit Your Malpractice Coverage?” text and legal papers, mug, pen, and books
September 16, 2026
Wondering if your dental malpractice premium still makes sense? See how our annual review and remarketing process works, and when to shop the market.
New York dentist reviewing a professional liability policy with a CFS Dental Division advisor in a M
September 9, 2026
Dental Malpractice Insurance in New York: What Every Dentist Should Know
California dentist reviewing a professional liability insurance policy with a CFS Dental Division ad
September 9, 2026
A plain English look at how dental malpractice insurance works in California, plus the questions our team walks through with practice owners. Let's talk.
September 2, 2026
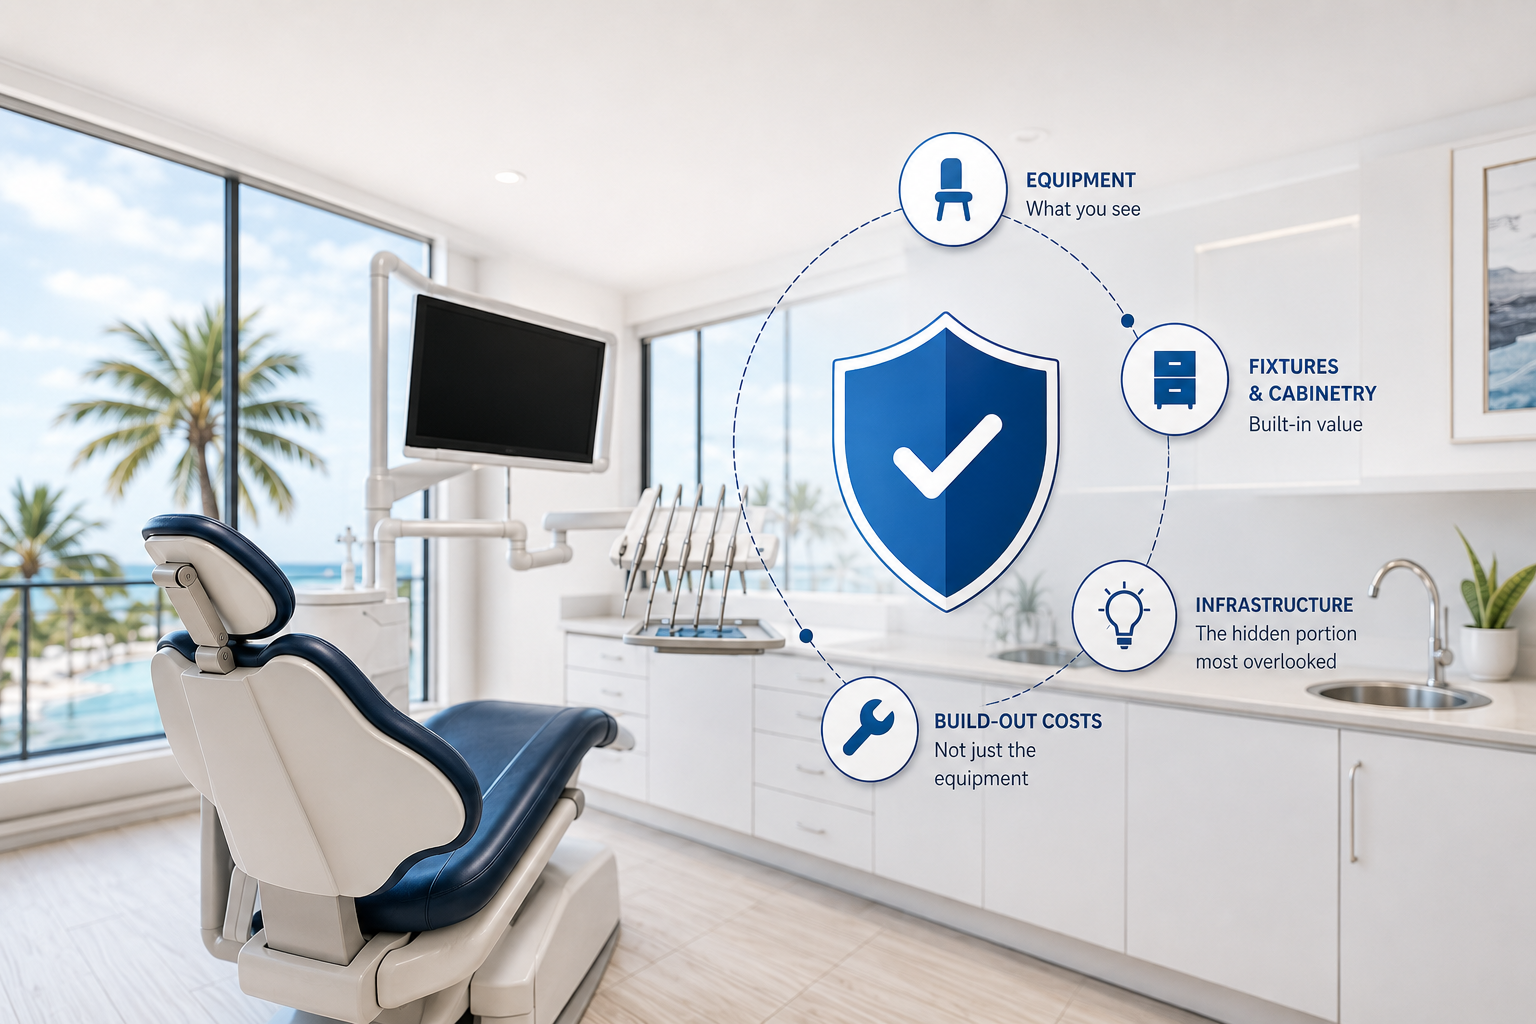
How much is enough? Defining business personal property and uncovering the “hidden” portion many practice owners miss
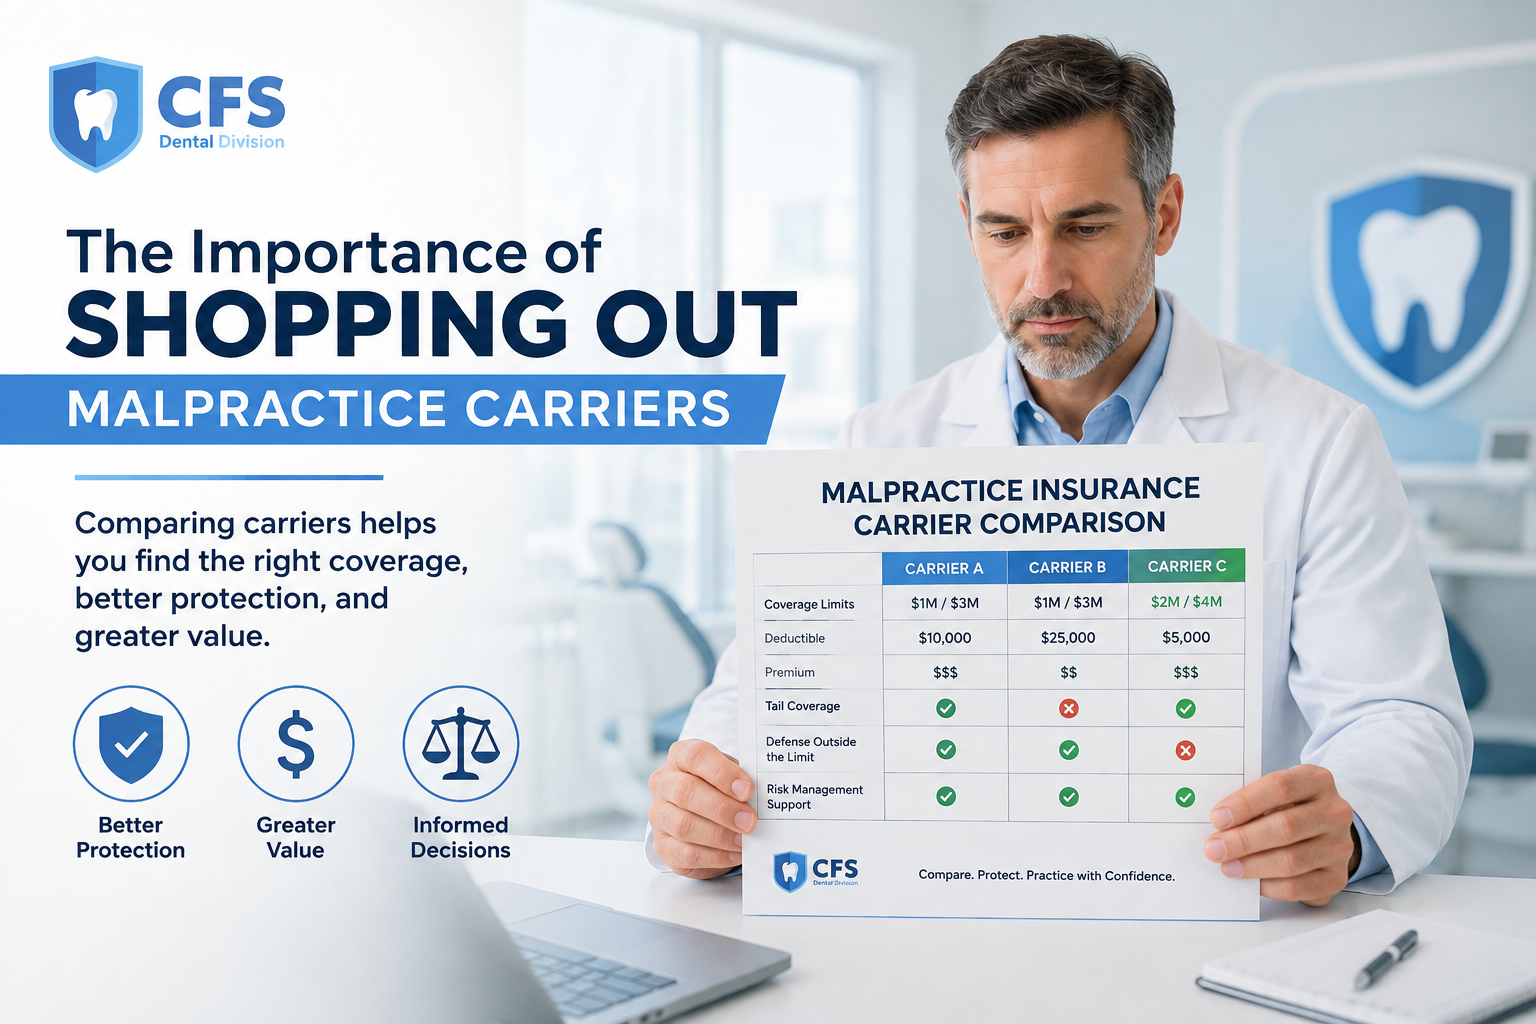
Poster about shopping out malpractice carriers, with a man holding a comparison chart beside a laptop.
September 2, 2026
The Importance of Shopping Out Malpractice Carriers
By Matthew Christy • August 6, 2026
Surplus Lines Insurance: What It Is, Why It Exists, and When You Might Need It
By Nick Cepparulo • July 21, 2026
Why Focusing on Protection - Not Just Price - Is Most Important When Buying Business Insurance For Your Dental Practice.
By Julia Breneman • July 15, 2026
Buying Your First Dental Practice: An Insurance Checklist for New Owners
By Eric Harper • July 9, 2026
Claims Made vs. Occurrence Malpractice Policies:  Exploring Your Options Without Fear
More Posts