Why Personal Life Insurance Gives Power Back To You!

Dentistry is a high-income, highly skilled profession that positions individuals for long-term success. During dental school and residency, speakers often emphasize the importance of practice management and financial management as central pillars of a successful career. However, one of the more challenging conversations involves personal life insurance. Proper planning in this area allows dentists to protect themselves enabling them to focus on what they do best — caring for patients.
Contact Us Today
Life insurance is a risk management tool, not just a formality. By understanding its mechanisms and protective benefits, individuals can harness life insurance as a valuable asset that supports them throughout various phases of their career.
Compared to many other professionals, dentists typically enter the workforce with significant student loan debt, often ranging from $100,000 to $600,000 or more. After graduation, additional financial responsibilities can follow quickly, including purchasing a home or acquiring a dental practice. Carrying such a heavy debt load early on can make dentists, and their families, more vulnerable to financial strain if unexpected events occur and proper planning is not in place. Dentists can secure life insurance early in their career and use it as a protective tool if circumstances do not go as planned.
NOT ONE-SIZE-FITS-ALL
Life insurance is not one-size-fits-all, especially for dentists whose financial responsibilities tend to grow rapidly. The two of the most common types of life insurance are Term Life and Whole Life, and each serves a different purpose within a dentist’s overall financial plan.
TERM LIFE INSURANCE
Term life insurance provides coverage for a specific period of time, commonly 10, 15, 20, or 30 years. If the insured passes away during that term, the policy pays a death benefit to the beneficiaries. Term life insurance is often the most cost-effective way to obtain a large amount of coverage, making it especially valuable during high-liability years. It can help protect a spouse or family while student loans, a mortgage, or practice debt are still outstanding. Term life insurance ensures loved ones are not burdened with debt or forced to make significant lifestyle changes should the unexpected happen. Some Term policies are also convertible, allowing dentists to convert term coverage into whole life insurance later without additional medical underwriting—an attractive option for future practice owners who may want access to cash value in the future.
WHOLE LIFE INSURANCE
Whole life insurance, on the other hand, provides lifelong coverage. In addition to a guaranteed death benefit, Whole life policies build cash value over time. This cash value grows on a tax-advantaged basis and can be accessed during the insured’s lifetime through policy loans or withdrawals. For dentists with stable income and long-term planning goals, Whole life insurance can serve as both a protection and a cash accumulation tool supporting legacy planning, future expenses, or conservative diversification alongside traditional investments.
LIFE INSURANCE WORKS FOR YOU
The most effective strategy is not choosing one option over the other but understanding how each fits into different stages of life. Discussing life insurance can often feel uneasy because it requires contemplating potential future situations that no one wants to imagine. However, life insurance ultimately empowers dentists to pursue their goals confidently, knowing their loved ones and financial obligations will be protected.
Written by: Julia Breneman
Wondering if your dental malpractice premium still makes sense? See how our annual review and remarketing process works, and when to shop the market.
Dental Malpractice Insurance in New York: What Every Dentist Should Know
A plain English look at how dental malpractice insurance works in California, plus the questions our team walks through with practice owners. Let's talk.
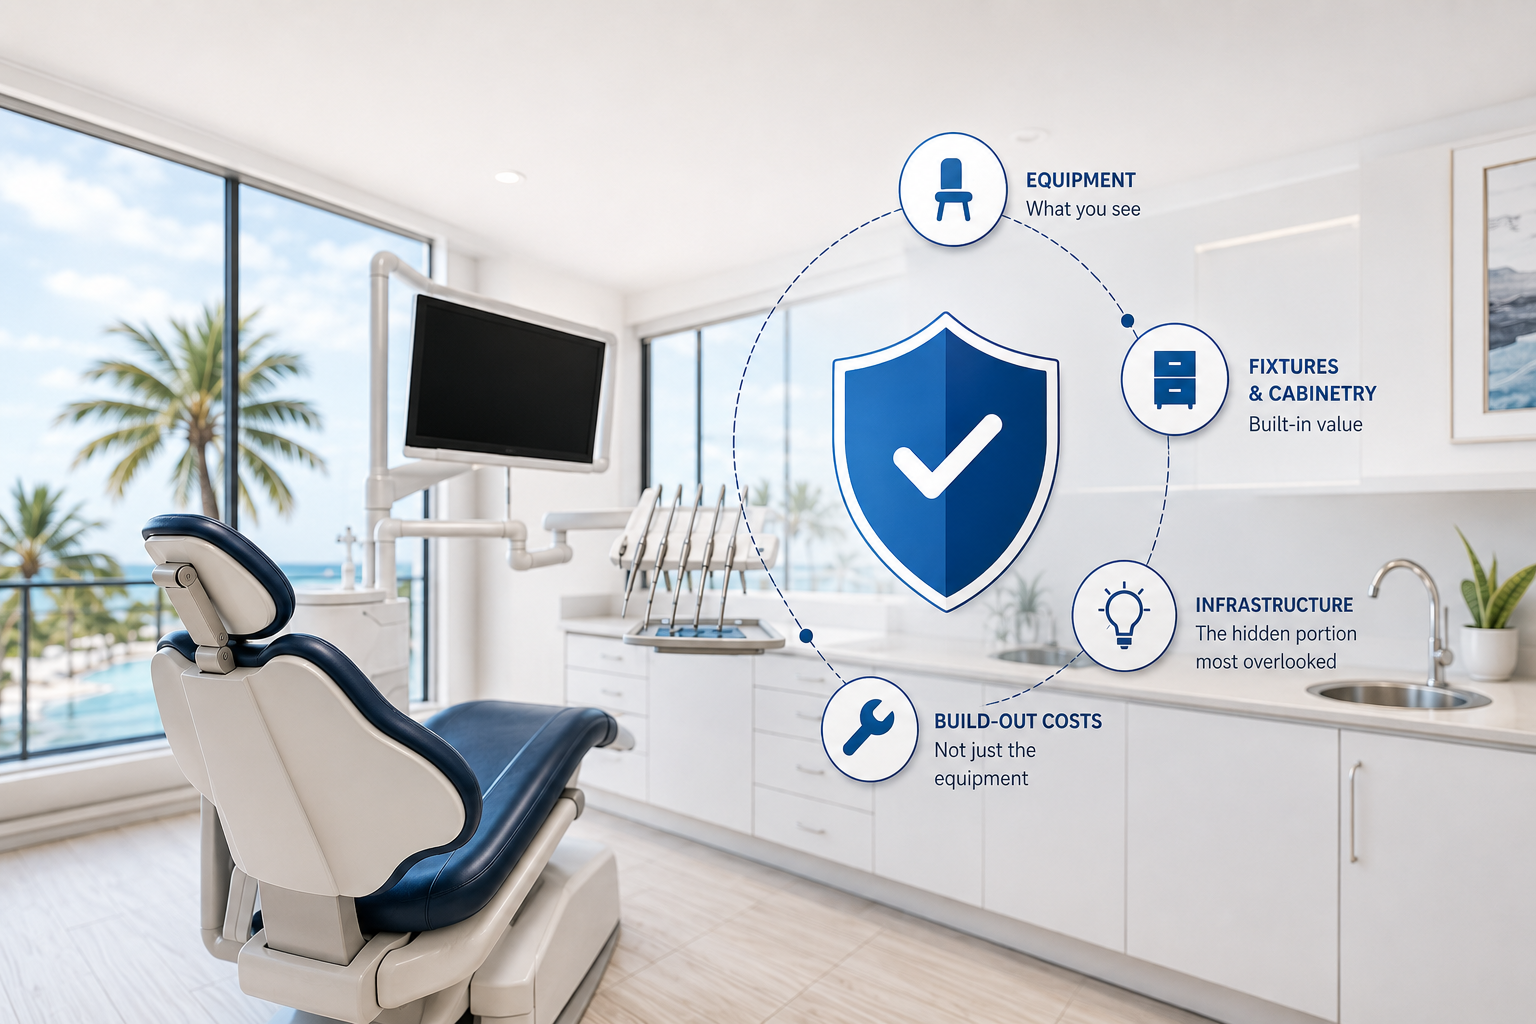
How much is enough? Defining business personal property and uncovering the “hidden” portion many practice owners miss
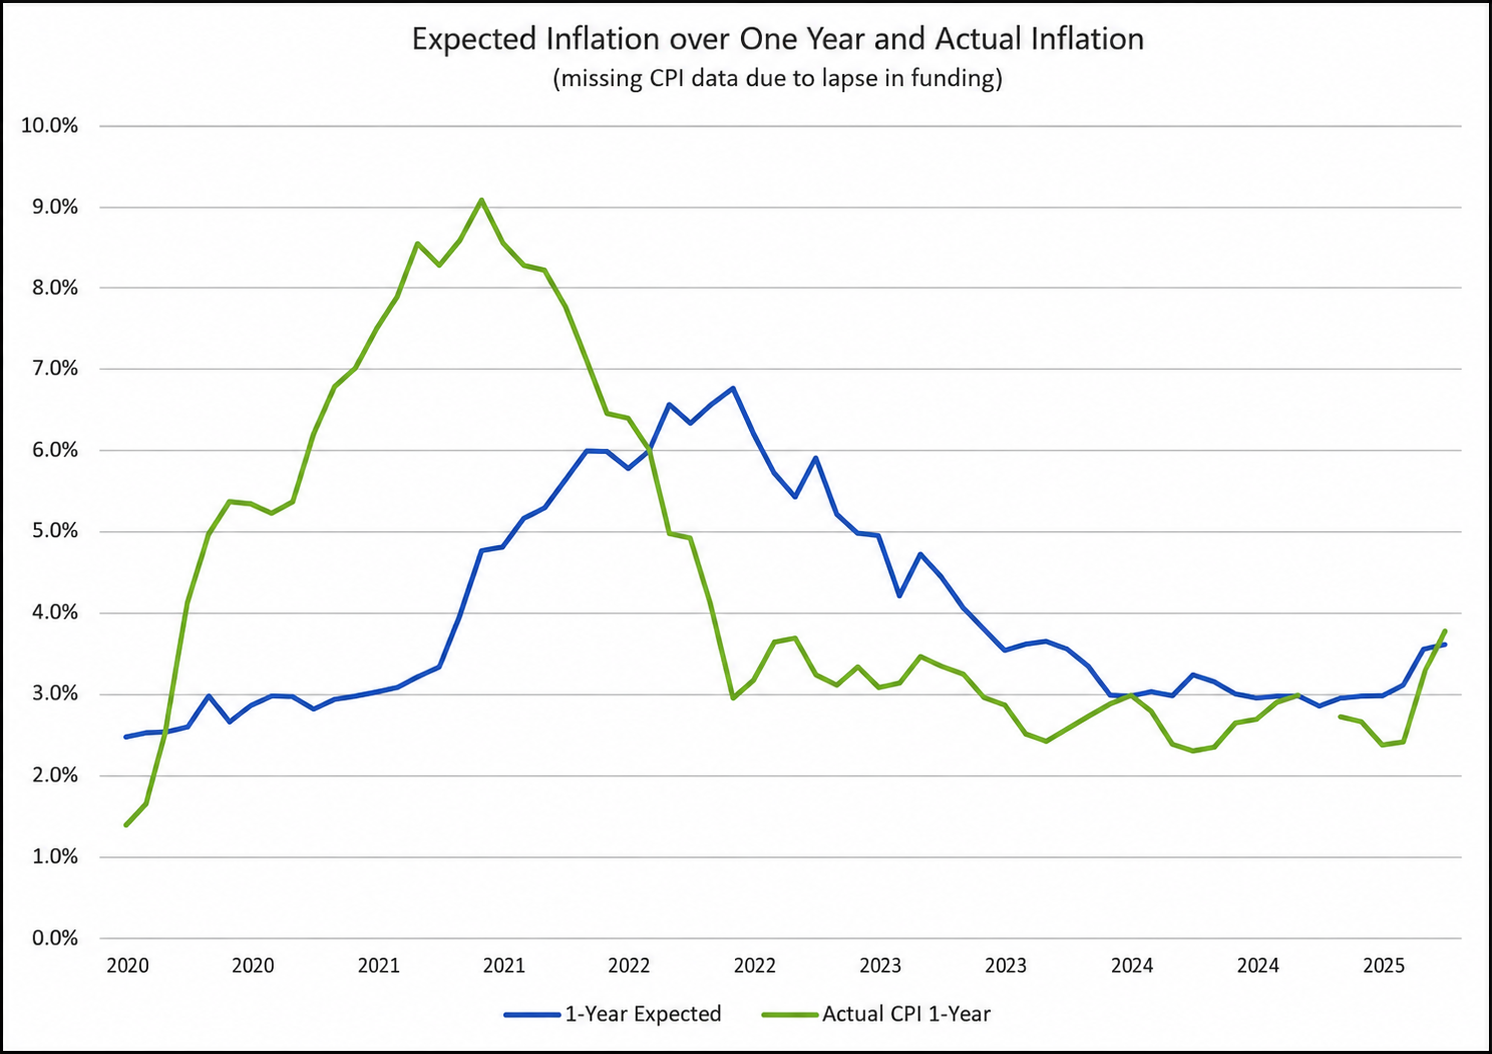
The Benefits of COLA
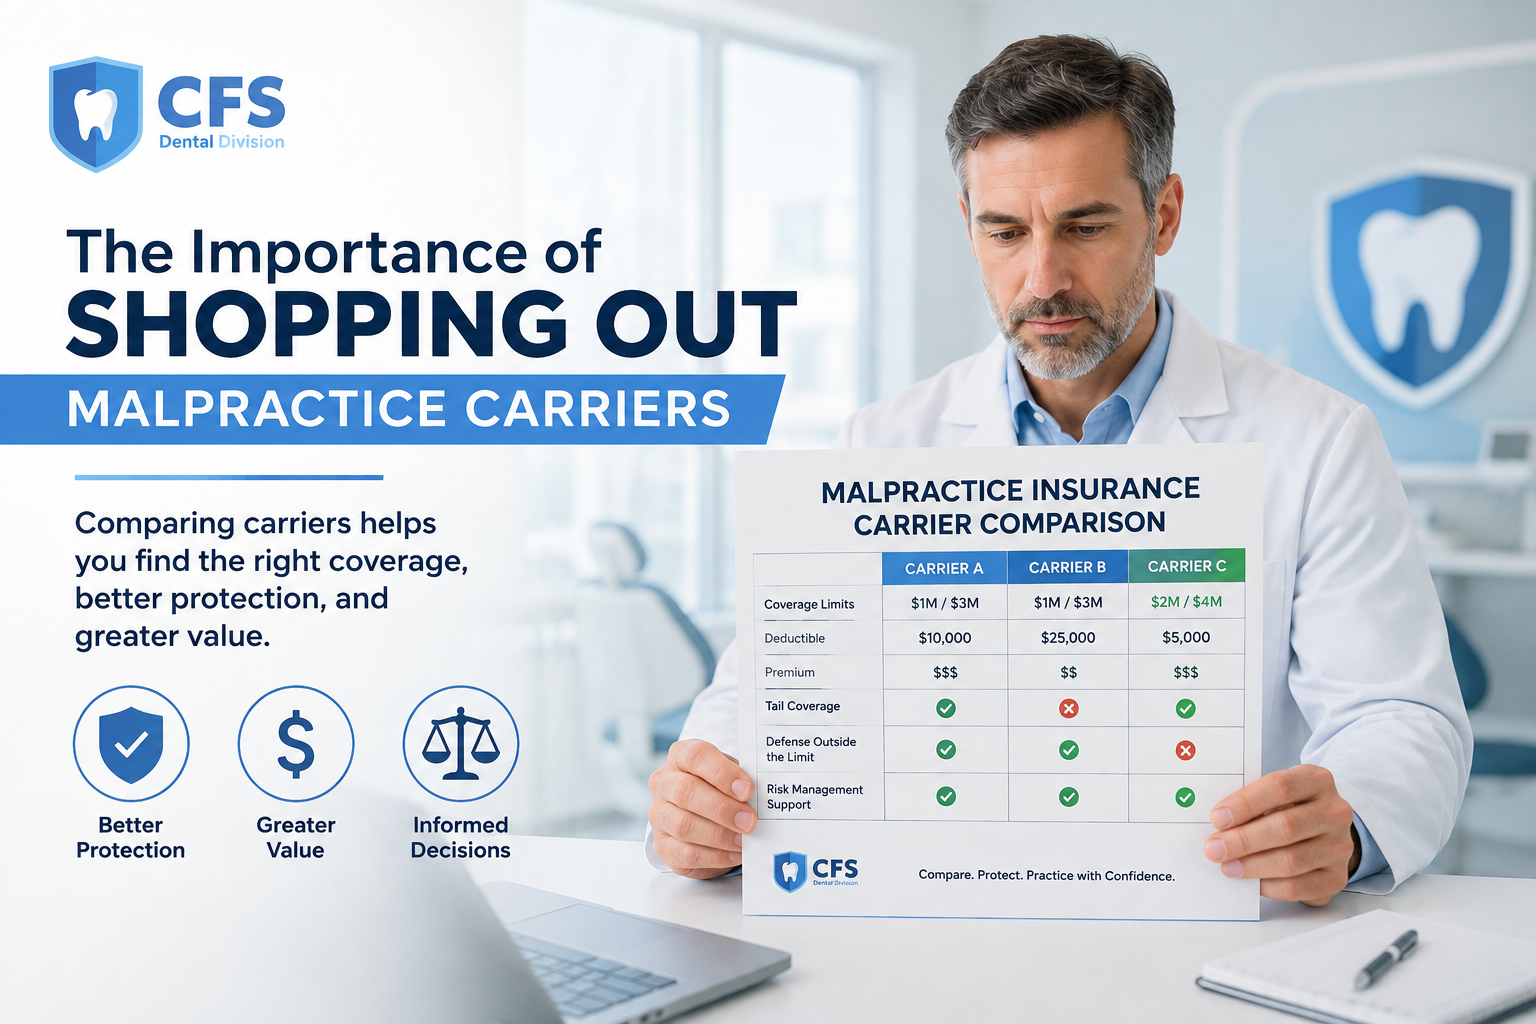
The Importance of Shopping Out Malpractice Carriers
Surplus Lines Insurance: What It Is, Why It Exists, and When You Might Need It
Why Focusing on Protection - Not Just Price - Is Most Important When Buying Business Insurance For Your Dental Practice.
Buying Your First Dental Practice: An Insurance Checklist for New Owners
Claims Made vs. Occurrence Malpractice Policies: Exploring Your Options Without Fear